Autopilot Accounting: Five Planning Rituals That Reveal a Company Running on Memory
Photo: financial spreadsheets budget planning desk calculator business, via img.freepik.com
Every fall, American companies engage in an elaborate ceremony called annual planning. Spreadsheets multiply, meetings stretch across calendars, and by December a document exists that will govern next year's resource allocation. Yet in many organizations, the outcome was never really in doubt. The rituals below are the tell — each one a habit that feels like diligence but is actually a sign the organization has substituted memory for judgment.
1. Last Year Plus Five Percent
The most common budgeting method in corporate America is also the least defensible: take last year's actuals, add a growth percentage, distribute. It feels prudent. It is really an abdication.
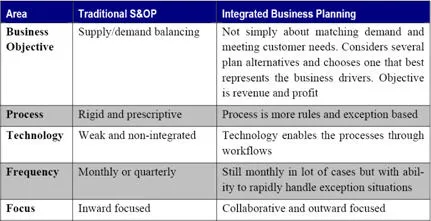
What it conceals: the assumption that last year's resource allocation was correct, which it almost never was. Every legacy program, every headcount inherited through an acquisition, every subscription nobody remembers purchasing gets renewed by default. The cost is not the five percent — it is the hundred percent of last year's mistakes carried forward with interest. The honest alternative is zero-based review of a meaningful slice of the budget each year, forcing every significant line to justify itself against current strategy rather than historical precedent.
2. The Sandbagged Ask
Department heads know the game. Request 120 percent of what you need, expect to be cut to 90, and land roughly where you should have started. Finance knows the game too, and quietly shaves every submission by a rule-of-thumb discount.
What it conceals: the real priorities. When every number is inflated as a negotiation position, leadership loses the signal it needs most — which teams genuinely cannot deliver with current resources and which are padding. The cost is chronic misallocation dressed up as fiscal discipline. The alternative is a culture where finance publishes its own independent estimate before hearing requests, and variances are debated openly rather than gamed in advance.
3. The December Spend-Down
Nothing reveals a broken planning system like the year-end scramble to exhaust remaining budget before it disappears. Teams that would never request funds mid-year for a needed tool will spend furiously in the final two weeks to avoid returning a surplus that would justify a cut next cycle.
What it conceals: a perverse incentive embedded in the planning process itself. If underspending is punished and overspending is forgiven, managers will rationally waste money in December rather than save it in June. The cost is real cash — often millions across a large enterprise — converted into low-value purchases purely to protect next year's baseline. The alternative is simple: allow departments to carry a defined portion of unspent funds forward, and celebrate returned budget instead of suspecting it.
4. The Sacred Line Item
Every organization has them: budget lines that survive every cycle, every leadership change, every strategic pivot, untouched and unquestioned. Ask why, and the answer is some version of "we've always funded that."
What it conceals: the org chart's history rather than its future. Sacred line items are typically the residue of a departed executive's priority or a long-completed initiative that never got a sunset review. The cost is opportunity — every dollar defended by tradition is a dollar unavailable for the strategy leadership says it is pursuing. The alternative is an annual sunset list: any program without a named owner and current business case goes on the table by default.
5. The Plan That Dies in January
The final ritual is the quietest: a budget built with genuine care in October that is functionally obsolete by the first quarter, adjusted thereafter through an endless stream of off-cycle reallocation memos nobody tracks.
What it conceals: the absence of any living connection between planning and operations. If the plan cannot absorb new information without a formal amendment process, managers will simply route around it — and the budget becomes historical fiction. The cost is not just financial; it is the credibility of the entire planning function in the eyes of the people it governs. The alternative is a rolling forecast refreshed quarterly, with the annual budget serving as a starting hypothesis rather than a twelve-month contract.
The Common Thread
None of these rituals persists because leaders are careless. They persist because they are comfortable — they reduce conflict, protect incumbents, and make an inherently uncertain exercise feel orderly. But order without judgment is not discipline; it is autopilot. The companies that plan well are not the ones with the most elaborate templates. They are the ones willing to let the plan be argued with, changed, and occasionally wrong.